
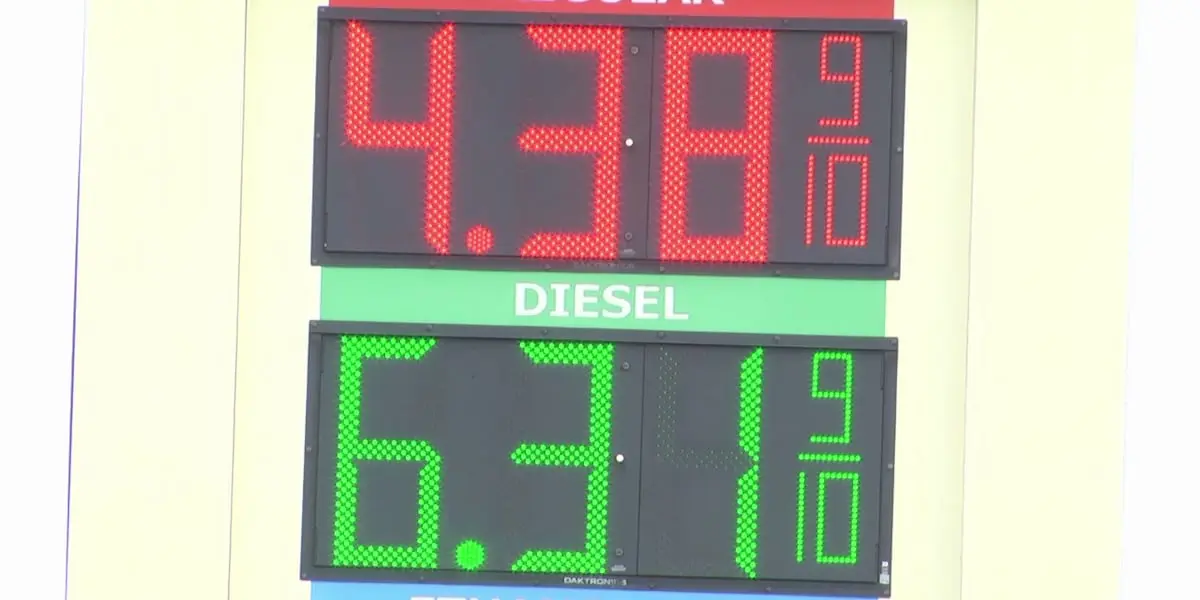

OCALA, Fla. — The economic shockwaves of historic fuel inflation are reverberating across the United States, as diesel prices surge to unprecedented levels. According to market intelligence data compiled by GasBuddy, the national average for a gallon of diesel hit a staggering $6.43 on Friday morning, marking a sobering milestone for an economy heavily dependent on freight transportation.
While average prices at the pump vary slightly by region—with Florida motorists and trucking fleets experiencing some minor relief at roughly 10 cents below the national benchmark—the overarching narrative remains grim. For logistics providers, independent owner-operators, and everyday consumers, the unrelenting climb in fuel costs is no longer just a transportation sector crisis; it has evolved into a broad-based economic emergency that threatens to further fuel persistent inflationary pressures.
Executive Overview
The rapid escalation of diesel prices serves as the lifeblood of commerce and has placed an unsustainable burden on the nation’s supply chain. Virtually every consumer good—from fresh produce and household cleaning supplies to construction materials and apparel—relies on diesel-powered heavy-duty trucks at some stage of its journey from manufacturer to retail shelf.
When the cost of operating these commercial vehicles skyrockets, the financial impact cascades rapidly through the entire economic ecosystem. Local freight carriers, already operating on razor-thin profit margins, are facing compounding operational deficits. To survive, these companies are forced to pass exorbitant fuel surcharges down the line to distributors, retailers, and, ultimately, the end consumer.
Industry insiders warn that what begins as a fuel price hike inevitably transforms into higher prices for groceries, elevated housing and construction costs, and increased expenses for all shipped goods. As fleet operators grapple with thousands of dollars in weekly deficit spending, economists fear that sustained high diesel prices could act as a severe brake on economic growth, potentially pushing vulnerable businesses toward insolvency and deepening the financial squeeze on households already grappling with broader cost-of-living increases.
Detailed Chronology: The Escalation of the Fuel Crisis
To understand the severity of the current crisis, it is necessary to examine the trajectory of fuel markets over the past several years. The warning signs of a looming diesel shortage began manifesting well before the current record-breaking highs, driven by a complex convergence of geopolitical instability, post-pandemic demand spikes, and domestic refining capacity constraints.
Early Warning Signs and Pandemic Rebounds
As global economies aggressively reopened following the initial waves of the COVID-19 pandemic, industrial production roared back to life. This sudden surge in global manufacturing dramatically accelerated the demand for energy commodities. However, global petroleum refining capacity had contracted during the pandemic lockdowns, creating a fundamental supply-demand imbalance.
By late 2021 and early 2022, distillate fuel inventories—which include diesel and heating oil—began trending significantly below five-year historical averages. Unlike gasoline, which is primarily consumed by passenger vehicles, diesel is the primary fuel for heavy-duty commercial trucks, agricultural machinery, construction equipment, and trains. Consequently, any contraction in diesel supply immediately threatens the foundational machinery of the global economy.
Geopolitical Shocks and Export Pressures
The situation deteriorated significantly following geopolitical conflicts in Eastern Europe, which disrupted international crude oil markets and led to sweeping sanctions on major petroleum exporters. European nations, heavily reliant on Russian diesel imports, scrambled to secure alternative supplies from the global market, competing directly with domestic American buyers.
This international scramble for refined products caused wholesale diesel prices to detach from broader crude oil trends. Even when crude oil prices experienced temporary plateaus or minor dips, diesel refining margins—known as the "crack spread"—remained abnormally elevated. Refiners were incentivized to export diesel to regions commanding the highest prices, tightening domestic inventories within the United States to historically low levels.
The tipping point: 2024 to 2026
By early 2026, the cumulative weight of these systemic pressures pushed prices past psychological tipping points. In Ocala, Florida, a critical logistics and distribution hub in the central part of the state, local businesses watched in dismay as prices climbed week after week. By early Friday morning, local pump prices were hovering dangerously close to the national average of $6.43 per gallon.
For commercial carriers, this meant that routine cross-country hauls or regional distribution runs transformed from manageable operational expenses into massive financial liabilities. The chronic nature of the price increases eliminated the possibility of absorbing the costs through short-term budgeting adjustments, forcing companies into defensive survival modes.
Supporting Context & Metrics: The Anatomy of a Logistics Crisis
The impact of $6.43-per-gallon diesel is best understood through hard economic metrics and the day-to-day realities of fleet management. In the logistics sector, fuel is traditionally the second-largest variable expense after labor, typically accounting for 20% to 30% of a carrier’s total operating budget. When fuel prices double or triple over a relatively short timeframe, that percentage skews dramatically, consuming operating capital meant for equipment maintenance, insurance premiums, and driver wages.
Local Impact: Suncoast Express Case Study
To grasp the human and operational toll of these market dynamics, one must examine regional operators on the front lines. Suncoast Express, a prominent local trucking company based in Florida, provides a clear lens into the crisis.
According to company representatives, the financial math of running a commercial fleet has been upended. Since January alone, the baseline cost to fill a standard commercial semi-truck’s dual fuel tanks has ballooned by more than $500 per fill-up. For a medium-sized fleet operating multiple vehicles on continuous regional routes, this translates to an astonishing weekly increase in operational expenses ranging between $5,000 and $10,000.
"Until you see it in the grocery store. Until you see it in your housing costs. Whatever it may be. It starts with us, I guess you could say," notes Dylan Dennid of Suncoast Express.
Dennid highlights the impossible paradox facing carriers today: "If we go cheaper, or we stay at the same price, we’re losing money, you know. So we just have to let them go [clients] or pay the higher prices. So we can stay alive at the company."
This ultimatum illustrates the difficult choices confronting independent carriers and mid-sized fleet operators across the country. Absorbing the cost is a direct path to bankruptcy; passing the cost along risks losing contracts to larger conglomerates or depressing shipping volumes altogether.
The Macroeconomic Ripple Effect
The metrics of high diesel prices extend far beyond the trucking yard. Economists utilize transportation cost indices as a leading indicator for retail inflation. Consider the logistics lifecycle of a standard consumer good:
- Raw Materials: Raw components are hauled via diesel truck or rail to manufacturing plants.
- Finished Goods: Completed products are transported from factories to distribution warehouses.
- Regional Distribution: Goods are moved from warehouses to retail distribution centers.
- Last-Mile Delivery: Items are delivered to local storefronts or residential doorsteps.
With diesel costs embedded at every single tier of this supply chain, the compounding effect means that a significant jump in fuel prices multiplies geometrically by the time a product reaches the shelf. This structural reality explains why consumers are seeing persistent price increases across retail sectors, even when other inflationary pressures appear to be moderating.
Official Statements and Industry Perspectives
As the crisis deepens, industry associations, economists, and logistics executives are calling for targeted policy interventions and greater transparency within the energy markets.
The American Trucking Associations (ATA)
The American Trucking Associations has repeatedly emphasized that the nation’s supply chain is uniquely vulnerable to fuel price volatility. In statements addressing the current pricing climate, ATA leadership has pointed out that America’s 3.5 million professional truck drivers move roughly 72.6% of the nation’s freight by weight.
"When diesel prices reach these unsustainable heights, it places an immediate, crushing tax on the entire supply chain," an ATA spokesperson noted in a recent industry briefing. "Independent owner-operators—who comprise a significant percentage of our workforce and operate on extremely tight cash flows—are being forced to park their trucks because they simply cannot secure the working capital required to fill their tanks."
Energy Analysts and Refining Sector Response
Energy market analysts attribute the persistent price strength to a combination of constrained domestic refining capacity and robust global demand for middle distillates. Despite calls from lawmakers to increase domestic crude oil production, industry experts note that the primary bottleneck is not crude extraction, but rather the capacity and utilization rates of domestic refineries capable of cracking crude oil into high-purity diesel fuel.
Environmental regulations, aging refinery infrastructure, and corporate capital discipline focused on shareholder returns rather than massive multi-year capital expenditures have kept domestic refining capacity constrained. Consequently, refiners are operating at high utilization rates to meet demand, leaving little cushion for unexpected refinery outages, severe weather events along the Gulf Coast, or geopolitical supply disruptions.
Future Outlook: Navigating Uncertainty
Looking ahead, stakeholders across the energy, transportation, and retail sectors face a landscape defined by acute uncertainty. Without a sudden, dramatic expansion in global refining capacity or a significant cooling of worldwide demand for distillates, analysts warn that high diesel prices may persist through the near term.
Potential Pathways for Relief
- Refining Capacity Expansion: Bringing idled refining capacity back online or expanding existing distillation units could help alleviate the supply crunch, though such projects require significant time and capital investment.
- Alternative Fuel Adoption: While long-term investments in electric and hydrogen-powered commercial fleets are accelerating, the transition timeline for heavy-duty long-haul trucking remains measured, meaning the sector will remain heavily dependent on petroleum diesel for years to come.
- Monetary and Fiscal Adjustments: Policymakers may face renewed pressure to evaluate temporary tax holidays or strategic reserve releases targeted specifically at distillate fuels, though such measures are often debated regarding their long-term efficacy versus market distortion.
The Consumer Outlook
For the average consumer, the immediate future suggests continued vigilance at the checkout counter. As long as transport companies like Suncoast Express are forced to navigate weekly expense increases of $5,000 to $10,000 just to keep their trucks moving, the cost of commerce will remain elevated.
Ultimately, the record-breaking surge in diesel prices serves as a stark reminder of the fragile interdependencies powering the modern economy. Until stability returns to the fuel markets, the burden of $6.43 diesel will continue to be shared by everyone who relies on the trucks that keep America moving.

0 Comments