

Executive Overview
The United States Department of Agriculture (USDA), in conjunction with the Federal State Inspection Service, has officially lowered its projections for the 2026 domestic peanut crop. Released amid the early stages of the annual harvest season, the latest crop production figures indicate a significant contraction in both total yield and overall production volume compared to initial expectations and prior-year benchmarks.
According to the updated federal reporting, the 2026 U.S. peanut crop has been pegged at approximately 5.27 billion pounds. This reflects a notable reduction of 152,000 pounds from the August projections, driven primarily by localized weather pressures, lowered per-acre yields, and a continued contraction in total planted acreage. Total planted acreage for the current marketing year stands at 1.41 million acres—a 1% decrease from the previous month’s estimates and a staggering 28% drop relative to the previous year.
While per-acre yields remain marginally higher than those recorded during the same period last year, the dramatic reduction in harvested footprint guarantees a tighter forward balance moving into the next marketing cycle. Despite these tightening supply fundamentals, the physical cash market for peanuts has experienced a period of relative calm as producers across the key growing regions transition their focus from field management to active harvesting operations. This report provides an in-depth, investigative look into the driving factors behind the USDA’s downward revisions, examining the underlying metrics, historical comparisons, and broader implications for domestic and international agricultural markets.
Detailed Chronology of the 2026 Peanut Production Revisions
To fully understand the trajectory of the 2026 U.S. peanut crop, it is necessary to examine the chronological progression of federal crop estimates, weather developments, and agronomic challenges that have shaped the current agricultural landscape.
Pre-Planting and Spring Outlook (January – April 2026)
As agricultural producers finalized their crop rotations and input purchasing decisions early in the year, early market signals pointed toward a cautious reduction in peanut acreage. Driven by shifting commodity prices—particularly competing input costs and favorable returns for alternative row crops like cotton and corn—growers signaled an intention to scale back. Fertilizer costs, equipment maintenance, and fluctuating water availability in key irrigated regions further compounded strategic planting adjustments.
The Summer Growing Season and August Baseline (May – August 2026)
By mid-summer, the USDA established its baseline estimates for the 2026 crop, setting the stage for what federal analysts anticipated would be a manageable, albeit smaller, harvest. Throughout June and July, weather patterns across the primary peanut-producing states—spanning the Southeast, the Southwest, and the Virginia-Carolina regions—exhibited notable variability.
While certain pockets enjoyed timely summer rains, others faced prolonged dry spells and high ambient temperatures during critical pegging and pod-filling stages. Despite these localized stress factors, the August federal report initially projected stable overall production metrics, keeping figures near the higher end of the mid-summer spectrum at 5.27 billion pounds, albeit built upon a shrinking acreage foundation.
The September Adjustments and Harvest Initiation (September 2026)
The turning point in the seasonal narrative arrived with the release of the September federal crop production report, compiled using field data and producer surveys up to September 1. The inspection services and USDA data crunchers adjusted figures downward, shaving 152,000 pounds off the national total compared to the August iteration.
This downward adjustment directly reflected deteriorating yield conditions in select production corridors and confirmed that planted acreage had contracted further than anticipated. As combines and diggers rolled into fields across the Sunbelt during mid-September, the market absorbed the reality of a 27% year-over-year drop in total production volume, setting the stage for a structurally tighter supply environment heading into the winter months.
Supporting Context & Metrics: Analyzing the Numbers
A rigorous examination of the USDA and Federal State Inspection Service data reveals the true magnitude of the 2026 production adjustments. The interplay between acreage contraction, shifting yield averages, and historical comparisons underscores a pivotal season for the U.S. peanut industry.
Acreage Contraction: A 28% Year-Over-Year Decline
The most striking metric in the 2026 crop report is the steep reduction in planted acreage. Total planted land dedicated to peanuts has fallen to 1.41 million acres. This figure represents:
- A 1% month-over-month decline from the August estimates.
- A dramatic 28% decrease when compared to the total acreage planted during the previous production year.
This widespread reduction in acreage is not uniform across all growing regions. The Southeast—traditionally the powerhouse of U.S. peanut production, encompassing states such as Georgia, Florida, Alabama, and Mississippi—experienced notable shifts as farmers reallocated land to optimize operational profitability. Similar acreage contractions were observed in the Southwest (Texas, Oklahoma, and New Mexico) and the Virginia-Carolina region (Virginia, North Carolina, and South Carolina), where water rights, crop rotation requirements, and rotational disease management play critical roles in land allocation.
Yield Dynamics: Quality Versus Quantity
While total acreage has plummeted, per-acre yield metrics present a more nuanced picture. In the August report, the national average yield was projected at 3,956 pounds per acre. However, the September 1 data update lowered this expectation to 3,879 pounds per acre.
Despite this month-over-month decline, the current yield estimate still outpaces the performance seen at the same point last year:
- The 2026 September yield projection of 3,879 pounds per acre remains 111 to 112 pounds per acre higher than the comparable figures from the previous season.
Agronomist evaluations suggest that while total plant populations and pod counts in stressed dryland fields fell short of optimal targets, well-managed irrigated acres performed exceptionally well, pulling the national average above last year’s baseline. Nevertheless, the net loss in per-acre potential between August and September—driven by late-season heat stress and inadequate rainfall in un-irrigated sectors—was sufficient to drag overall production totals down.
Total Production Volume and Forward Balance
When synthesizing the reduced acreage (1.41 million acres) with the adjusted average yield (3,879 pounds per acre), the total U.S. peanut production for 2026 is forecast at 5.27 billion pounds.
- This represents a 27% drop in total volume compared to the previous year’s harvest.
- The smaller absolute crop size directly points to a lesser forward balance moving into the next marketing year, tightening ending stocks and influencing domestic utilization and export capabilities.
| Metric | Previous Month (August) | Current Estimate (September) | Year-Over-Year Change |
|---|---|---|---|
| Planted Acres | 1.42 million | 1.41 million | -28% |
| Average Yield | 3,956 lbs/acre | 3,879 lbs/acre | +111 to +112 lbs/acre |
| Total Production | ~5.27+ billion lbs | 5.27 billion lbs | -27% |
Official Statements and Industry Response
The release of the revised USDA data has prompted reactions from agricultural economists, industry associations, and market analysts who monitor the pulse of the U.S. peanut complex.
Market observers note that despite the downward revisions, the physical cash market has remained remarkably subdued. Tyron Spearman, agricultural reporter for Southeast AgNet, highlighted this dynamic in his field reporting, observing:
"The peanut market is very quiet right now as farmers move into the field and start harvesting this crop, but the estimate so far has been lowered."
This initial market tranquility can be attributed to the timing of the report. As harvest operations get underway, many producers and shellers are primarily focused on the logistical execution of lifting, drying, and grading the incoming crop rather than aggressive forward contracting. Furthermore, buyers and processors often maintain a cautious posture until field-run samples provide concrete data regarding actual grade, kernel size distribution, and outturn percentages.
Agricultural economists emphasize that while the immediate spot market reflects a "wait-and-see" attitude, the fundamental reality of a 27% year-over-year reduction in total production volume cannot be ignored. Grain and oilseed analysts point out that lower ending stocks will inevitably provide underlying support to grower pricing structures as the marketing year progresses and the supply pipeline begins to reflect the contraction.
Future Outlook: Implications for Growers, Processors, and Consumers
As the 2026 harvest gains momentum across the American agricultural belt, stakeholders across the supply chain must navigate the strategic implications of a tighter peanut supply.
Impact on Agricultural Producers
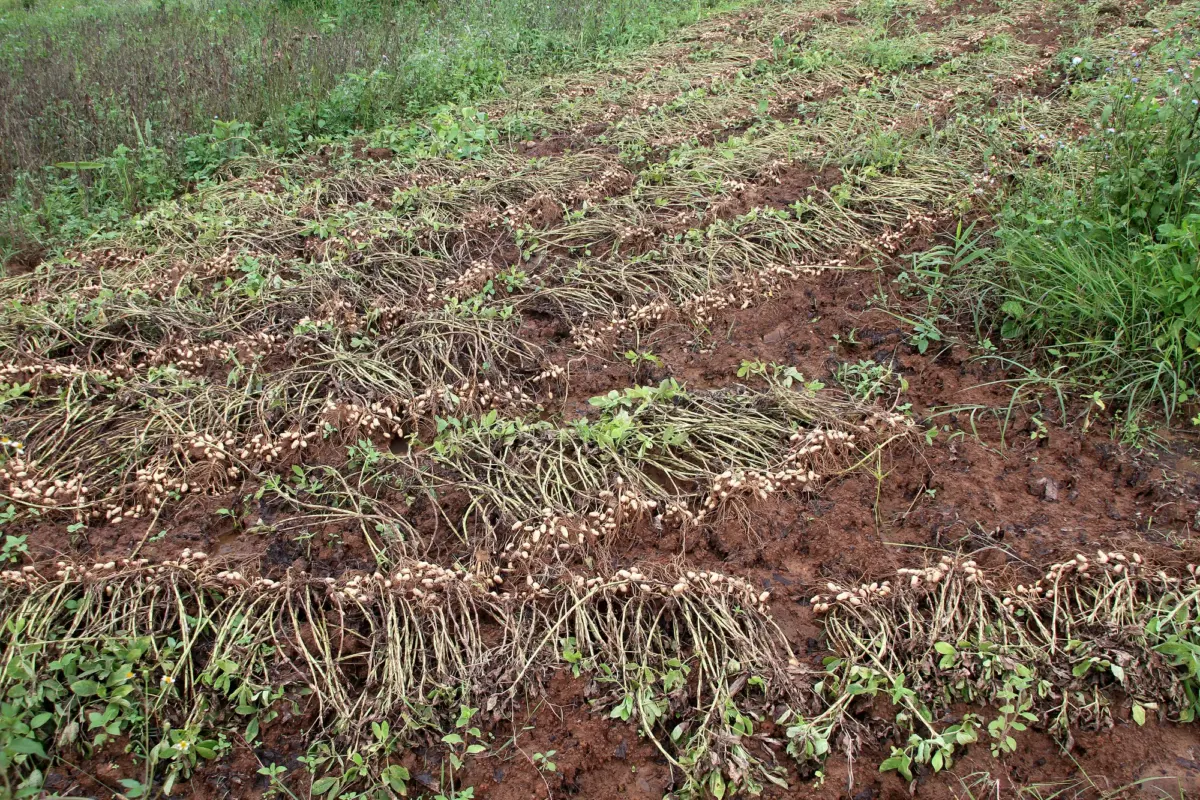
For peanut farmers, the 2026 season underscores the delicate balance between input cost management and yield optimization. With total acreage down significantly, growers who successfully navigated weather challenges and optimized their irrigated fields are positioned to capture favorable market dynamics. However, dryland producers who faced severe weather anomalies may experience constrained revenues despite higher per-acre yields relative to last year, simply due to the lower baseline acreage. As harvest concludes, producers will closely evaluate input pricing, seed availability, and rotational crop returns in preparation for the 2027 planting cycle.
Implications for Shellers and Food Manufacturers
Shellers, product manufacturers, and exporters face a markedly different supply environment compared to the previous year. With total production capped at approximately 5.27 billion pounds and forward balances tightening, procurement managers will need to adopt disciplined inventory strategies. The reduction in available volume may lead to increased competition for high-quality farmer stock peanuts, particularly for specialized kernel sizes demanded by the confectionary, snack, and peanut butter manufacturing sectors. Export markets, which rely heavily on consistent U.S. supply for high-grade edible peanuts, may also experience tighter availability and shifting price realizations.
Consumer Price Sensitivities
For the end consumer, the transmission of agricultural commodity shifts to retail grocery shelves typically involves a lag period governed by existing inventory contracts, processing costs, and retail pricing strategies. While the immediate impact of the USDA’s downward production revision may not trigger sudden price spikes at the supermarket, the underlying fundamentals—specifically a 27% reduction in annual crop volume—suggest that cost pressures will remain elevated across the peanut product spectrum. Manufacturers will continue to absorb or pass along the costs associated with tighter domestic supplies and broader macroeconomic pressures.
Conclusion
The USDA and Federal State Inspection Service’s September update on the 2026 U.S. peanut crop paints a clear picture of an agricultural sector adjusting to reduced acreage and late-season yield recalibrations. With total production forecast at 5.27 billion pounds—down 27% from the previous year—and planted acreage contracting to 1.41 million acres, the industry is transitioning into a structurally tighter supply era.
Although the physical cash market remains quiet as combines roll through the fields of the Sunbelt, the underlying fundamentals mandate careful monitoring by producers, processors, and market analysts alike. As harvest data continues to flow in over the coming weeks, the true extent of grade quality and actual outturns will provide the definitive roadmap for the U.S. peanut complex through the remainder of the 2026–2027 marketing year.

0 Comments