

Executive Overview
As millions of aging adults approach their post-career golden years, a universal question lingers on the horizon: Where will we live, and how much space do we actually need? For generations, the conventional wisdom of retirement planning has pointed squarely toward downsizing. The narrative is as familiar as it is seductive—trade the sprawling family home for a sleek, low-maintenance condo, unlock decades of accumulated home equity, slash utility bills, and banish weekend lawn-mowing chores to the history books.
However, as contemporary economic pressures, shifting real estate landscapes, and complex personal dynamics collide, financial planners and senior living experts are urging a more cautious, nuanced approach. Downsizing is not a universal panacea. While trading down can provide vital liquidity and operational ease, it frequently carries hidden financial burdens, logistical nightmares, and emotional tolls that catch retirees completely off guard.

This comprehensive analysis examines the multifaceted pros and cons of downsizing in retirement. By evaluating the true financial realities, lifestyle trade-offs, and long-term implications of moving versus aging in place, this report aims to equip prospective retirees with the insights needed to make an informed, sustainable choice for their future.
Detailed Chronology of the Retirement Housing Decision
The path to deciding whether to downsize rarely happens overnight. It typically evolves through distinct life stages as homeowners transition from active careers to full-time retirement. Understanding this trajectory can help individuals anticipate challenges before they materialize.

Phase 1: The Pre-Retirement Contemplation (5 to 10 Years Prior)
Long before the moving trucks arrive, the idea of downsizing typically begins as a vague thought during weekend chores. Cleaning out gutters, paying hefty property tax bills, and maintaining empty bedrooms once occupied by grown children prompt couples to ask: Do we really need all this space? During this phase, homeowners often begin casually browsing real estate listings, tracking neighborhood home values, and fantasizing about a simpler lifestyle in a warmer climate or a vibrant urban center.
Phase 2: The Financial and Logistical Awakening (1 to 3 Years Prior)
As retirement approaches, the abstract idea of moving transforms into concrete financial planning. This is the critical juncture where individuals must evaluate their net worth tied up in home equity versus projected retirement income. It is also when the hidden costs of real estate transactions—such as realtor commissions, closing costs, and capital gains considerations—come into sharp focus.

Phase 3: The Sorting and Purging Process (Months Before the Move)
For many, this is the most emotionally and physically grueling chapter of the timeline. Decades of accumulated possessions, sentimental family heirlooms, and garage clutter must be sorted, categorized, and discarded. Homeowners quickly discover that adult children often have little interest in inheriting older furniture or bulky keepsakes, forcing difficult decisions about what stays and what goes.
Phase 4: The Transition and Settlement
The physical relocation marks the end of one era and the beginning of another. Whether moving into a single-story suburban cottage, a downtown high-rise apartment, or an active adult retirement community, the newly downsized retiree enters an adjustment period. This phase tests whether the anticipated reduction in stress and expenses matches the reality of living in a smaller, unfamiliar space.

Supporting Context & Metrics: The Financial and Lifestyle Equation
To accurately weigh the decision to downsize, retirees must dissect both the balance sheet and the day-to-day realities of living in a smaller footprint.
The Pros: Why Downsizing Still Appeals
- Unlocking Home Equity: For most homeowners, their primary residence represents their largest single store of wealth. Selling a high-value home and purchasing a less expensive dwelling frees up significant capital. This liquidity can be reinvested to generate passive retirement income or used to fund travel, healthcare, and leisure pursuits. (Caveat: This financial windfall is heavily dependent on regional real estate markets; moving from a low-cost area to a high-cost metropolis can easily erase anticipated savings).
- Lower Monthly Overhead: In theory, smaller footprints demand fewer resources. Utility bills for heating and cooling plummet, property taxes generally decrease, and homeowners insurance rates drop.
- Drastically Reduced Maintenance: The endless cycle of home upkeep comes to an end. Smaller yards require minimal lawn care, and moving into a condominium, apartment, or managed retirement community often shifts exterior maintenance—such as roof repairs, snow removal, and landscaping—entirely off the homeowner’s plate.
- Liberation from Material Clutter: Purging decades of accumulated belongings is frequently described by retirees as psychologically liberating. Furthermore, minimizing personal possessions relieves grieving heirs of the burdensome task of sorting through an estate later in life.
- Optimized for Aging in Place: Traditional multi-story homes can become hazardous obstacles for aging bodies. Downsizing offers the ideal opportunity to transition to a single-story floor plan or a home equipped with zero-step entries, wider doorways, lever door handles, and accessible bathroom facilities, ensuring safety if mobility aids become necessary.
- Proximity to Essential Services: Relocating to a well-connected community places seniors within walking distance or a short transit ride of medical providers, pharmacies, grocery stores, and vibrant senior centers that offer both social activities and vital support services.
The Cons: The Hidden Costs and Realities
- The Exorbitant Cost of Moving: Many retirees fail to budget adequately for the sheer expense of relocation. Realist commissions, moving company fees, estate sales, property transfer taxes, and the cost of minor renovations or new furnishings for the new space can easily consume up to 10% of the original home’s value.
- Pre-Sale Home Improvements: A home lived in for decades often accumulates deferred maintenance. While minor cosmetic flaws or aging fixtures might not bother the current owner, a real estate agent will likely demand fresh paint, new carpeting, and modern upgrades before putting the property on the market—requiring significant out-of-pocket cash investments.
- The Logistics and Emotional Toll of Relocation: Packing a lifetime of memories into boxes is physically exhausting and emotionally draining. Letting go of sentimental items triggers profound nostalgia. Moreover, changing utility accounts, updating addresses, and learning to navigate an unfamiliar neighborhood can induce severe relocation stress.
- Creeping Monthly Fees: While utility bills may drop, moving into a condominium or retirement community introduces homeowners association (HOA) or monthly management fees. These fees are often substantial, tend to rise steadily over time, and can easily outpace any savings achieved on utilities. Additional costs for parking spaces or extra storage units can further inflate monthly expenses.
- Inherited Property Problems: Purchasing a "new-to-you" home does not guarantee a hassle-free existence. Older properties can harbor hidden structural defects, failing HVAC systems, aging roofs, or outdated plumbing. If major repairs or custom remodeling are required, initial financial savings can evaporate overnight.
- Loss of Personal Space for Couples: Spending 24/7 together in retirement requires a delicate balance. In a spacious home, spouses can retreat to separate rooms to pursue hobbies, read, or enjoy quiet time. In a significantly smaller dwelling, the lack of private zones can lead to friction and cabin fever.
- Emotional Attachment and Social Disruption: Leaving behind familiar neighbors, beloved local spots, and a home filled with decades of cherished memories is emotionally difficult. Rebuilding a social network from scratch in a new location takes time and intentional effort.
Expert Insights and Guidance
Navigating the housing maze requires objective tools rather than emotional guesswork. Financial researchers and retirement architects emphasize that the decision to downsize must be grounded in comprehensive financial modeling.

Experts frequently recommend utilizing specialized analytical tools, such as the Move or Stay Put calculators provided by financial literacy platforms, which allow homeowners to run side-by-side cost projections over a 10-to-20-year horizon. These calculators factor in appreciation rates, transaction costs, maintenance inflation, and tax implications to reveal the true long-term financial winner.
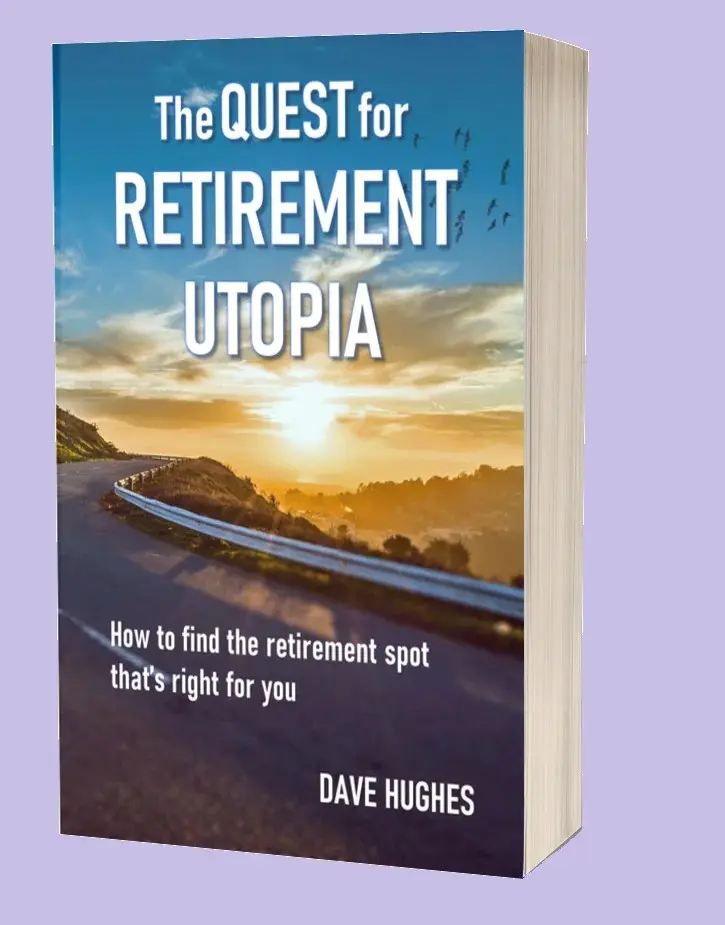
For those seeking a broader philosophical and strategic framework, thought leaders have dedicated entire volumes to the subject. For instance, in his book The Quest for Retirement Utopia, retirement expert Dave Hughes explores the psychological and logistical dimensions of choosing where and how to live post-career. The text provides frameworks to help prospective retirees clarify their core values, evaluate potential destinations realistically, avoid catastrophic relocation mistakes, and identify environments that truly support long-term well-being.

Future Outlook: The Evolving Landscape of Senior Housing
As demographic shifts alter the real estate market, the future of retirement housing is evolving rapidly. With the massive Baby Boomer generation continuing to age, the demand for flexible, accessible, and community-oriented housing is at an all-time high.
Looking ahead, industry analysts predict several emerging trends:

- The Rise of "aging-in-place" retrofitting: Rather than packing up and moving, a growing number of retirees are choosing to invest their capital into remodeling their current multi-story homes—installing stairlifts, walk-in showers, and smart-home safety monitoring systems.
- Innovative co-housing models: Seniors are increasingly exploring alternative living arrangements, such as shared housing, multigenerational living, and pocket neighborhoods, which offer built-in social support without the isolation sometimes found in traditional retirement communities.
- Technology-enabled independence: Advances in telehealth, smart home automation, and on-demand local services are making it increasingly feasible for older adults to remain in their longtime homes safely and comfortably, altering the traditional cost-benefit calculation of downsizing.
Conclusion
Ultimately, downsizing is neither a guaranteed ticket to financial freedom nor an unnecessary hurdle. It is a deeply personal strategic choice that demands a careful, clear-eyed reconciliation of personal finances, physical capabilities, emotional readiness, and lifestyle desires. By weighing the hidden costs against the tangible benefits—and utilizing available financial calculators and expert resources—retirees can design a living arrangement that secures not only their financial future, but their peace of mind.

0 Comments