

Executive Overview
Tax season is an annual rite of passage that invariably induces stress, confusion, and anxiety for millions of American households. Whether you are a first-time filer attempting to decipher the complexities of an entry-level W-2 position or a seasoned veteran managing multiple streams of income, investments, and dependents, the landscape of federal taxation requires constant vigilance. Staying organized, understanding your fundamental obligations, and recognizing the wealth of credits and deductions available can transform an overwhelming administrative burden into an opportunity to secure financial well-being.
As the 2026 tax filing window opens, taxpayers face an evolving economic environment shaped by recent legislative adjustments, shifting inflation metrics, and new reporting standards for alternative income streams like the gig economy. While residents of states like Florida enjoy the distinct advantage of having no state-level personal income tax, the federal tax burden remains universal and demanding. Missteps—ranging from premature filing before all documentation has arrived to failing to account for self-employment quarterly liabilities—can result in processing delays, missed financial windfalls, or avoidable penalties from the Internal Revenue Service (IRS).
This comprehensive guide is designed to cut through the regulatory jargon and provide a definitive roadmap for the 2026 tax season. By examining the essential documentation required, understanding the mechanics of federal tax obligations, distinguishing between various types of tax credits, and exploring reputable free-filing resources such as VITA, AARP, and UF/IFAS programs, taxpayers can approach this season with absolute confidence and strategic clarity.
Detailed Chronology: Navigating the Tax Season Lifecycle
Successfully navigating tax season is not a singular event; rather, it is a structured, chronological process that begins months before the filing deadline and extends through the final reconciliation of your return. Understanding this lifecycle ensures that taxpayers avoid costly omissions and reactionary scrambles.
Phase 1: Preparation and Document Collection (January – February)
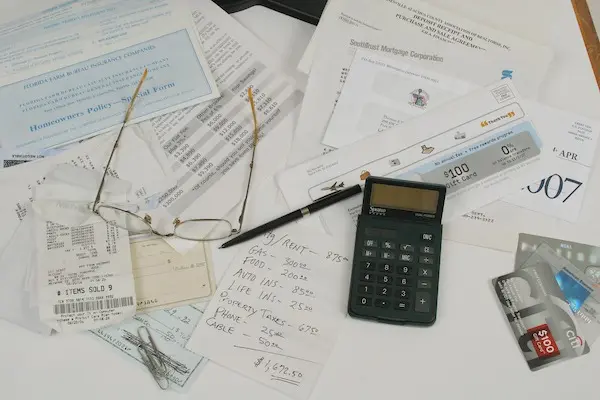
The foundation of an accurate tax return is the systematic accumulation of income and expense documentation. Rushing into the filing process before all forms have been issued is one of the most common—and damaging—mistakes a taxpayer can make.
Taxpayers must maintain a centralized, secure location—whether physical or digital—for every piece of incoming financial correspondence. The timeline for receiving these documents typically spans from late January through mid-February. Key forms to monitor and collect include:
- W-2 Forms: Detailing wages, salaries, and withheld taxes from traditional employers.
- 1099 Series Forms: Spanning interest income (1099-INT), dividends (1099-DIV), stock and investment sales (1099-B), retirement distributions (1099-R), unemployment compensation (1099-G), gig economy and freelance earnings (1099-K, 1099-MISC, and 1099-NEC), and gambling winnings (W-2G).
- Educational and Social Security Documentation: Forms such as the 1098-T for tuition and scholarships, and the SSA-1099 for Social Security benefit reporting.
- Deduction Records: Receipts for charitable donations, out-of-pocket medical expenses, mortgage interest statements (Form 1098), and local property tax records.
The Golden Rule of Filing: Never file your taxes until you have verified that every single expected document has arrived in your possession. Filing prematurely often necessitates filing an amended return (Form 1040-X), which delays refunds and increases the risk of IRS scrutiny.
Phase 2: Assessment and Obligation Review (February – March)
Once documentation is gathered, taxpayers must evaluate their structural tax position. In the United States, the tax system operates on a "pay-as-you-go" principle, meaning that income tax must be paid as you earn or receive income throughout the year.
For traditional wage earners, employers handle this via payroll withholding. However, for independent contractors, freelancers, and small business owners, this responsibility falls squarely on the individual. Utilizing tools like the IRS W-4 Estimator allows taxpayers to project their ultimate tax liability and adjust withholding mid-stream if necessary. Self-employed individuals must carefully review their compliance with quarterly estimated tax payments to avoid underpayment penalties.
Phase 3: Credit Optimization and Return Compilation (March – April)
With documentation complete and obligations understood, the focus shifts to tax optimization. This phase involves matching personal life circumstances with available federal tax credits. Unlike deductions, which lower your overall taxable income, credits offer a dollar-for-dollar reduction of your actual tax liability, making them exceptionally valuable.
Taxpayers must meticulously evaluate whether they qualify for nonrefundable credits (which can reduce tax liability to zero but yield no excess cash) or refundable credits (which can result in a direct financial refund even if no tax was owed).
Phase 4: Execution, Filing, and Post-Season Management (April and Beyond)
The final phase involves submitting the return via IRS Free File, commercial software, or professional assistance, followed by monitoring the status of your refund. For those who find themselves unable to file by the April deadline, applying for an extension is critical, though it is vital to remember that an extension to file is not an extension to pay any estimated taxes owed.
Supporting Context & Metrics: Understanding the Financial Landscape
To fully grasp the stakes of the 2026 tax season, it is helpful to examine the broader financial and geographic context in which taxpayers operate.

The Regional Advantage: State vs. Federal Obligations
Geographic location plays a significant role in tax complexity. Residents of states like Florida occupy a unique position: while they are subject to all federal income tax requirements, they benefit from the complete absence of a state-level personal income tax. This simplifies state-level compliance, allowing residents to direct 100% of their tax preparation focus toward federal obligations and local property taxes.
However, the absence of state income tax does not insulate individuals from federal auditing standards, self-employment taxes, or specialized federal levies. Furthermore, property taxes and sales taxes remain active revenue generators at the local and state levels, making organized record-keeping for mortgage and property tax statements (Form 1098 and county records) essential for those who choose to itemize deductions.
The Rise of Alternative Income and the 1099 Economy
The modern workforce has shifted dramatically over the last decade, with millions of Americans engaging in freelance work, ridesharing, content creation, and online commerce. This shift is clearly reflected in IRS data, which shows a massive expansion in the issuance of Form 1099-K and 1099-NEC documents.
Gig economy workers often struggle with the pay-as-you-go system because platforms typically do not withhold taxes on their behalf. Failing to set aside between 25% to 30% of gross freelance earnings for federal, state (where applicable), and self-employment taxes can lead to severe financial distress come April. Utilizing structured financial counseling and tracking deductible business expenses—such as home office use, vehicle mileage, and equipment purchases—is critical for mitigating this burden.
Comprehensive Overview of Major Tax Credits
Tax credits represent the most effective legal mechanism for reducing a tax burden. The federal tax code organizes these into two distinct categories:
-
Nonrefundable Tax Credits: These credits can reduce your tax liability down to $0, but any excess credit amount is forfeited. Examples include:
- Saver’s Credit (Retirement Savings Contributions Credit): Designed to encourage low- to moderate-income workers to save for retirement.
- Lifetime Learning Credit: Assists with undergraduate, graduate, and professional degree tuition and fees.
- Adoption Credit: Helps offset the often-substantial costs associated with adopting a child.
-
Refundable Tax Credits: These credits are far more advantageous because if the credit exceeds the amount of tax you owe, the difference is paid directly to you as a refund. Examples include:
- Child Tax Credit (CTC): Provides substantial financial relief to families raising dependent children.
- Earned Income Tax Credit (EITC): A vital antipoverty tool designed to support low- to moderate-income working individuals and couples.
- Child and Dependent Care Credit: Helps working parents cover the costs of daycare, babysitting, and care programs.
- American Opportunity Tax Credit (AOTC): A partially refundable credit for qualified education expenses during the first four years of higher education.
- Energy Credits: Incentivizing homeowners to invest in renewable energy sources, such as solar panels and energy-efficient home improvements.
Official Statements and Expert Guidance
Tax professionals, regulatory bodies, and community extension programs emphasize that education and early preparation are the ultimate antidotes to tax season anxiety.
According to financial literacy advocates and extension agents, many taxpayers leave hundreds—if not thousands—of dollars on the table simply due to a lack of awareness regarding available credits and free filing resources. The Internal Revenue Service consistently urges taxpayers to utilize authorized electronic filing options and secure online tools to minimize mathematical errors and accelerate refund processing times.
Furthermore, community outreach initiatives highlight the importance of localized support. Institutions such as the University of Florida’s Institute of Food and Agricultural Sciences (UF/IFAS) Extension provide crucial resources for residents navigating financial and tax-related challenges. Through local offices and specialized programs, experts offer guidance on budgeting, record retention, and connecting with certified tax preparation volunteers.
Free File Resources: Accessing Professional Help Without the Cost
Filing taxes does not have to be an expensive endeavor. Several premier, federally backed, and community-driven programs offer free assistance to eligible taxpayers, ensuring that professional guidance is accessible regardless of income level:
- VITA (Volunteer Income Tax Assistance): A longstanding IRS initiative that offers free tax help to people who generally make $64,000 or less, persons with disabilities, and limited-English-speaking taxpayers who need assistance preparing their tax returns. IRS-certified volunteers provide free basic income tax return preparation with electronic filing.
- AARP Tax-Aide: Primarily focused on taxpayers aged 50 and older or those with low-to-moderate income, this program provides free tax counseling and preparation assistance nationwide, operating in community centers, libraries, and other convenient locations.
- IRS Free File: A public-private partnership between the IRS and leading tax software providers, offering brand-name tax preparation software for free to individuals whose adjusted gross income (AGI) meets program thresholds. Additionally, Free File Fillable Forms are available to all taxpayers regardless of income.
- UF/IFAS Virtual VITA: For residents in Florida and surrounding regions, specialized academic and community extension initiatives—including virtual VITA programs—offer targeted assistance, helping local taxpayers navigate federal requirements securely and accurately.
Where to Find Local Assistance
If you find yourself facing complex tax scenarios, uncertain about your classification, or simply in need of a reassuring expert review before submission, help is readily available. Taxpayers are encouraged to reach out to their local UF/IFAS Extension office. Many of these offices maintain dedicated financial counseling units and can direct community members to accredited local tax preparation resources, ensuring that your 2026 tax season concludes smoothly, accurately, and with your financial interests fully protected.

0 Comments